Benchmarking Private Equity Cash Flow Forecasting: A Machine Learning Approach
Developing a machine learning framework to improve private equity liquidity modeling.
View Project →
We are the CEFS AI & Advanced Analytics Group at Technical University of Munich. We might be the largest team globally focused exclusively on quantitative alternatives assets research.
Private markets have become a core allocation for institutional investors. The evidence base underneath them has not kept pace.
Valuations are reported infrequently and smoothed. Much of what actually matters sits in written commentary and non-standardized documents rather than in structured data, so it never reaches the analysis.
Performance is largely reported by the managers being assessed, and selection and survivorship shape what is visible at all. Raw track records flatter, and the headline figures the industry leans on say surprisingly little about what comes next.
We are a research group first. Our work runs from building the underlying data to producing evidence that holds up academically and speaks to practice.
Three steps, applied to the three questions that define every private markets portfolio.
We build our own datasets and work with transaction records, fund cash flows, investor reporting, and firm financials, turning unstructured and non-standardized material into structured, analysis-ready data.
Econometrics, machine learning, and simulation applied across private equity, venture capital, and private debt, built to be interpretable rather than black boxes.
Peer-reviewed research on the three questions that sit behind every private markets portfolio, and the lens we bring to all of our work.
Measurement & Prediction
We treat risk as something to be modeled, not assumed. Machine learning and Bayesian methods turn valuation uncertainty and tail exposure in illiquid portfolios into numbers investors can act on.
Alpha Discovery & Value Creation
Alpha isn't luck. It's decomposable. We separate true value creation from selection skill, mapping exactly where private market returns come from.
Capital Flow & Allocation
Capital lock-up shouldn't be a black box. We model secondary markets and capital flows to give investors a clear-eyed view of liquidity, including when and how their money comes back.
Our quantitative toolkit mapped to the core research questions we pursue.
Hover a method or topic to trace its connections.
Tap a method or topic to see its connections.
A living research agenda across private equity, venture capital, and private markets more broadly.
Developing a machine learning framework to improve private equity liquidity modeling.
View Project →Developing a framework to integrate illiquid alternative assets into portfolio optimization, enhancing efficiency while accounting for risk, return, and liquidity.
View Project →Analyzing how private equity ownership drives firm growth while reducing short-term productivity in Europe.
View Project →A finding that stays in a working paper changes nothing. Ours travels in two directions, and both feed back into the work.
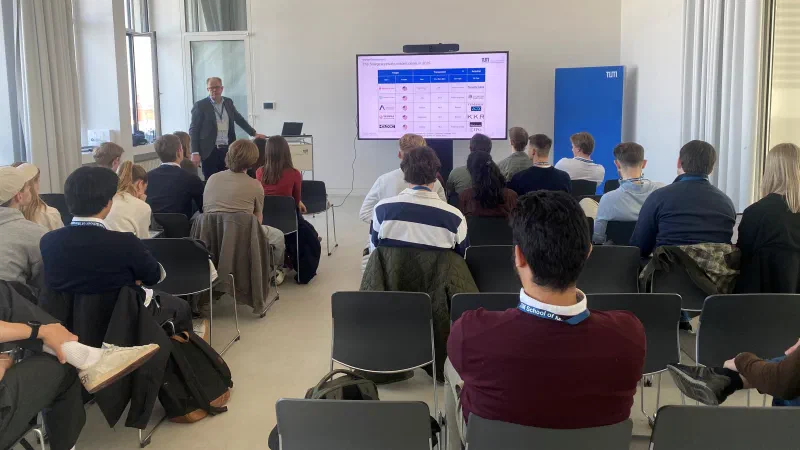
We teach entrepreneurial finance at the TUM School of Management, and current research goes straight into the material rather than waiting years for a textbook.
We work with institutional investors and industry partners on the questions they actually face, which keeps the research anchored in real data and real decisions.
We work with leading academic institutions and industry partners to advance private markets research, and we are always open to new collaborations.